If you’ve watched your 401(k) swing with the market and wondered whether part of it belongs in something steadier, you’re not alone. A 401(k) to gold IRA rollover lets you move retirement savings into physical precious metals without paying taxes or penalties, as long as you follow the rules.
Those rules are where people get hurt. The wrong rollover type, a non-approved coin, or an unqualified storage setup can turn a tax-free move into a taxable event. This guide covers how the rollover works, what you can and can’t buy, what it costs, and how to avoid the common mistakes.
Last updated: October 2026. This article is educational, not financial, tax, or legal advice.
In this guide:
- What is a gold IRA rollover?
- Can you roll a 401(k) into a gold IRA?
- Direct vs. indirect rollovers
- Step-by-step process
- IRS rules for metals and storage
- Taxes and penalties
- Costs to expect
- Pros and cons
- Mistakes to avoid
- FAQ
What Is a Gold IRA Rollover?
A gold IRA is a self-directed individual retirement account that holds IRS-approved physical precious metals instead of, or alongside, stocks and funds. A gold IRA rollover moves money from an existing retirement account, such as a 401(k), 403(b), or TSP, into that account.
Despite the name, a gold IRA isn’t a separate kind of IRA. It’s a traditional or Roth IRA whose custodian allows alternative assets. That means the usual IRA rules on taxes, distributions, and required minimum distributions (RMDs) still apply.
Can You Roll Over a 401(k) to a Gold IRA?
Usually yes, but timing depends on your plan.
- Former employer’s 401(k): Generally the easiest case. Once you’ve left the job, you can typically roll the balance out.
- Current employer’s 401(k): Only if your plan permits an “in-service” distribution, which many plans limit to employees age 59½ or older. Check your plan document or ask HR.
- Roth vs. traditional: A traditional 401(k) rolls into a traditional gold IRA tax-free. A Roth 401(k) rolls into a Roth gold IRA. Moving pre-tax money into a Roth is a taxable conversion.
A rollover is not a contribution, so it doesn’t count against annual limits. For reference, the 2026 IRA contribution limit is $7,500 (plus a $1,100 catch-up at 50+), and the 401(k) employee deferral limit is $24,500 (plus an $8,000 catch-up, or $11,250 for ages 60 to 63).
Direct vs. Indirect Rollover: Why It Matters
| Direct rollover | Indirect (60-day) rollover | |
|---|---|---|
| How funds move | Plan sends money straight to your new custodian | Plan pays you; you deposit it yourself |
| Tax withholding | None | Mandatory 20% federal withholding on 401(k) payouts |
| Deadline | None | 60 days to complete the rollover |
| Risk | Lowest | Missed deadline or shortfall can be taxed, and penalized if you’re under 59½ |
Choose a direct rollover. With an indirect rollover, the plan withholds 20% before you ever see the money. To roll over the full balance, you’d have to replace that 20% from other funds within 60 days. Otherwise the withheld portion counts as a taxable distribution.
A common point of confusion: the “one rollover per 12 months” rule applies to IRA-to-IRA indirect rollovers. It doesn’t limit 401(k)-to-IRA rollovers, and direct trustee-to-trustee transfers aren’t affected either.
How to Do a 401(k) to Gold IRA Rollover: Step by Step
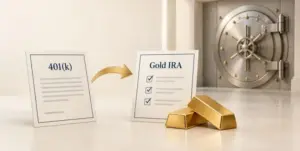
1. Confirm your plan’s rules. Ask your plan administrator whether you’re eligible to roll over, whether the plan allows in-service rollovers, and what paperwork it needs.
2. Choose a self-directed IRA custodian. Your IRA must be held by an IRS-approved custodian. You can’t hold it yourself. Confirm the custodian handles precious metals and ask for a written fee schedule.
3. Open the account. Choose traditional or Roth to match the source of your funds.
4. Request a direct rollover. Tell your plan administrator to send funds directly to the new custodian. Payment is typically made out to the custodian “FBO” (for the benefit of) you. Don’t have the check made out to you personally.
5. Select a precious metals dealer. The dealer sells the metals. The custodian pays for them from your IRA. Compare pricing, including the spread between the spot price and what you pay, and get all terms in writing.
6. Choose eligible metals. See the table below.
7. Arrange storage. The custodian arranges shipment to an approved depository, where your metals are held in your IRA’s name.
8. Keep records. Your plan reports the distribution on Form 1099-R, and your custodian reports the rollover on Form 5498. Keep both with your tax records.
The whole process often takes a few weeks, depending on how fast your plan releases funds.
IRS Rules: Approved Metals and Storage
Internal Revenue Code Section 408(m) generally bars IRAs from holding “collectibles.” It carves out exceptions for certain bullion and coins, which is why rare or numismatic coins usually don’t qualify.
| Metal | Minimum purity |
|---|---|
| Gold | 99.5% (.995) |
| Silver | 99.9% (.999) |
| Platinum | 99.95% (.9995) |
| Palladium | 99.95% (.9995) |
Notable exception: American Gold Eagle coins are 22-karat (about 91.67% gold), below the purity threshold, but federal law specifically permits them in IRAs. Other commonly approved products include Canadian Gold Maple Leafs and American Gold Buffalo coins, along with qualifying bars from accepted refiners. Always have your custodian confirm that a specific product is eligible before you buy.
Storage: IRA metals must be held by the trustee or custodian, typically in an approved depository. The “home storage gold IRA” pitch deserves skepticism. In McNulty v. Commissioner, the U.S. Tax Court held that IRA-owned gold stored under the account holder’s personal control was a taxable distribution. If anyone tells you home storage is safe, get a second opinion from a tax professional.
Taxes and Penalties
- Done correctly, a direct rollover is not taxable. Pre-tax to traditional is tax-deferred, and Roth to Roth stays tax-advantaged.
- Pre-tax to Roth is a conversion, and you owe income tax on the converted amount.
- Failed or improper rollovers can be treated as distributions, taxable as ordinary income, with a 10% additional tax if you’re under 59½ and no exception applies.
- RMDs apply. Gold IRAs are subject to required minimum distributions starting at age 73 (rising to 75 for those born in 1960 or later). You can take them in cash by selling metals, or in kind by taking the metals themselves, which is taxed at fair market value.
Because your situation determines the tax result, talk to a CPA or tax advisor before moving a large balance.
What Does a Gold IRA Cost?
Costs vary widely by provider. Ask each one for a written, itemized quote covering:
- Account setup fee (one-time)
- Annual custodian fee
- Storage fee (flat or based on the value of your metals)
- Insurance, if not included in storage
- Dealer markup or spread on purchase, and the buyback price if you sell
- Shipping and transaction fees
The spread is often the biggest cost and the easiest to overlook. A low advertised fee means little if the metals are priced well above spot.
Pros and Cons of Rolling a 401(k) Into Gold
Potential advantages
- Diversification beyond stocks and bonds
- A tangible asset with a long history as a store of value
- Possible inflation hedge, though results vary over time
- Tax-advantaged treatment inside the IRA
Potential drawbacks
- Gold pays no dividends or interest
- Prices can be volatile, and past performance doesn’t predict future results
- Fees and spreads are typically higher than for conventional funds
- Metals aren’t FDIC-insured
- You lose any employer match or low-cost institutional fund options on the rolled amount
Most financial professionals treat gold as a minority slice of a diversified portfolio rather than a replacement for it. You don’t have to roll over your whole 401(k). A partial rollover is common.
7 Mistakes to Avoid
- Choosing an indirect rollover and triggering withholding or a missed deadline
- Buying non-approved coins or collectibles
- Storing metals at home in an IRA
- Ignoring the spread and comparing only account fees
- Responding to high-pressure sales tactics. Consumer protection agencies have repeatedly warned about aggressive gold IRA marketing, so take your time and verify claims independently
- Rolling over too much without considering your overall allocation
- Skipping professional tax advice on a large rollover
Frequently Asked Questions
Can I roll over my 401(k) to a gold IRA without penalty?
Yes. A properly completed direct rollover from a 401(k) to a gold IRA is generally not taxable and carries no early withdrawal penalty.
Can I roll over a 401(k) while I’m still employed?
Only if your plan allows in-service distributions. Many plans restrict these to participants age 59½ or older.
Is there a limit on how much I can roll over?
No. The IRS doesn’t cap the amount of a 401(k)-to-IRA rollover. Annual contribution limits apply to new contributions, not rollovers.
How long does a 401(k) to gold IRA rollover take?
Often two to four weeks, depending on your plan administrator and custodian.
Can I hold physical gold at home?
Not safely inside an IRA. Metals must be held by an approved custodian or depository. See the McNulty discussion above.
Is a gold IRA a good idea?
It depends on your goals, time horizon, and risk tolerance. It can add diversification, but it carries costs and doesn’t produce income. Consider a fee-only financial advisor.
Can I roll a Roth 401(k) into a gold IRA?
Yes, into a Roth gold IRA. Rolling it into a traditional IRA isn’t permitted.
Disclaimer: This content is for informational purposes only and isn’t financial, tax, or legal advice. Consult a qualified professional before making retirement decisions.